ADVANCED MARQUIS, LLC Advanced Marquis LLC · Irvine, California
Irvine logistics warehouse with dock doors and trucks at still morning

ADVANCED MARQUIS, LLC — Irvine, California

Yield first. The building comes second.

We publish market insights and apply a disciplined approach to how commercial properties are evaluated before any discussion of a building itself. That order matters: a property can look sound on a tour and still fail on its numbers, its debt terms, or its local demand.

The pinned figure

What a property produces, in relation to its price — before hope about future rent growth.

Cap rate · NOI · Cash flow after debt

NOI income first Cash flow after debt Occupancy local read Debt terms in basis points

Commercial real estate in Irvine

ADVANCED MARQUIS LLC studies commercial real estate in Irvine

ADVANCED MARQUIS, LLC is a real estate investment company based in Irvine, California. Our work starts with the figures — cap rate, net operating income, cash flow, basis points, debt availability, occupancy and asset-class discipline — because those are the terms on which properties can actually be compared.

Why we start with the yield figure

A yield figure tells you what a property produces in relation to its price, before you account for hope about future rent growth. We pin that number first because it forces a comparison across properties that otherwise look nothing alike. Cap rate, net operating income, and the cost of debt sit side by side in that first pass. If the math is thin at the start, a newer lobby does not fix it. This is the habit behind the name of this site and the way our Irvine team reads a deal.

Market picture, 2026

The 2026 market picture, in plain terms

U.S. commercial real estate in 2026 is shaped by a recovery in transaction volume, financing that remains elevated but is stabilizing, and a clear split between sectors.

Some property types are supported by housing need, logistics demand, or limited new supply. Others face slower leasing or a heavier supply pipeline. That split is why we read sector reports instead of relying on a single national statement. The question is not whether the market is good or bad. The question is which part, where, and at what price.

Browse market insights

Investment volume

Investment volume measures how much property is changing hands. A rising figure suggests buyers and sellers are finding common ground on price — it does not mean every property is fairly priced.

Volume, read honestly

Volume can recover while cap rates stay cautious, because buyers still want a margin for uncertainty. We read volume as a sign of market function, not as proof of value. Price discipline still decides whether a purchase makes sense.

Financing

Debt terms still vary by property type, location and sponsor strength, so we check financing in basis points and in total cost before we judge a deal.

Asset-class discipline

What commercial real estate means in practice

Commercial real estate covers multifamily housing, retail centers, office buildings, and industrial and logistics space. Each type earns income differently, leases on different terms, and responds differently to interest rates. We keep those differences visible in every comparison — lumping all four sectors into one headline hides the decision you actually have to make.

See the sectors we follow

Industrial & logistics — high ceilings, truck access

Logistics
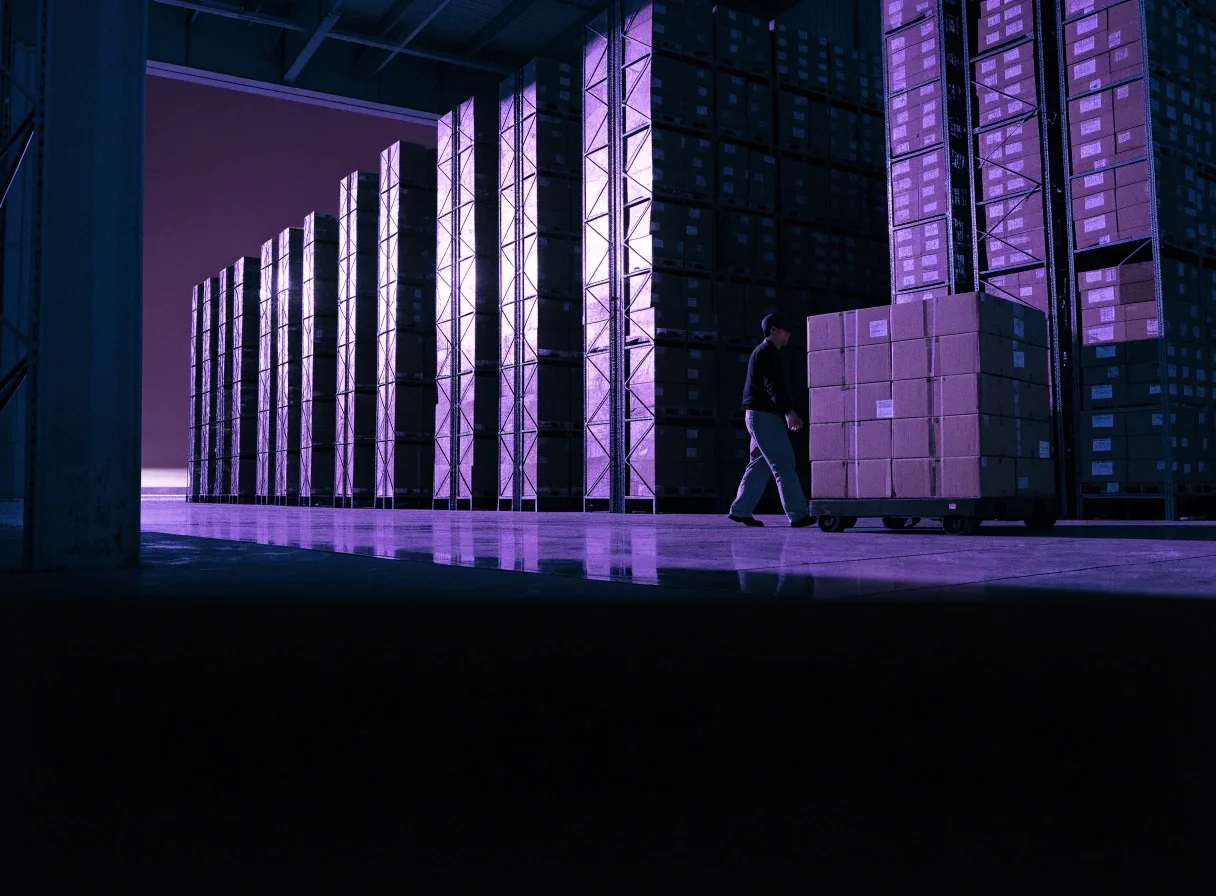
Warehouse interior with racking and a worker moving goods

An industrial tenant may need high ceilings and truck access that an office tenant does not. Scale, dock access and corridor demand do the work here, so we judge the building by how goods move through it.
Multifamily — housing need and leasing demand

Multifamily

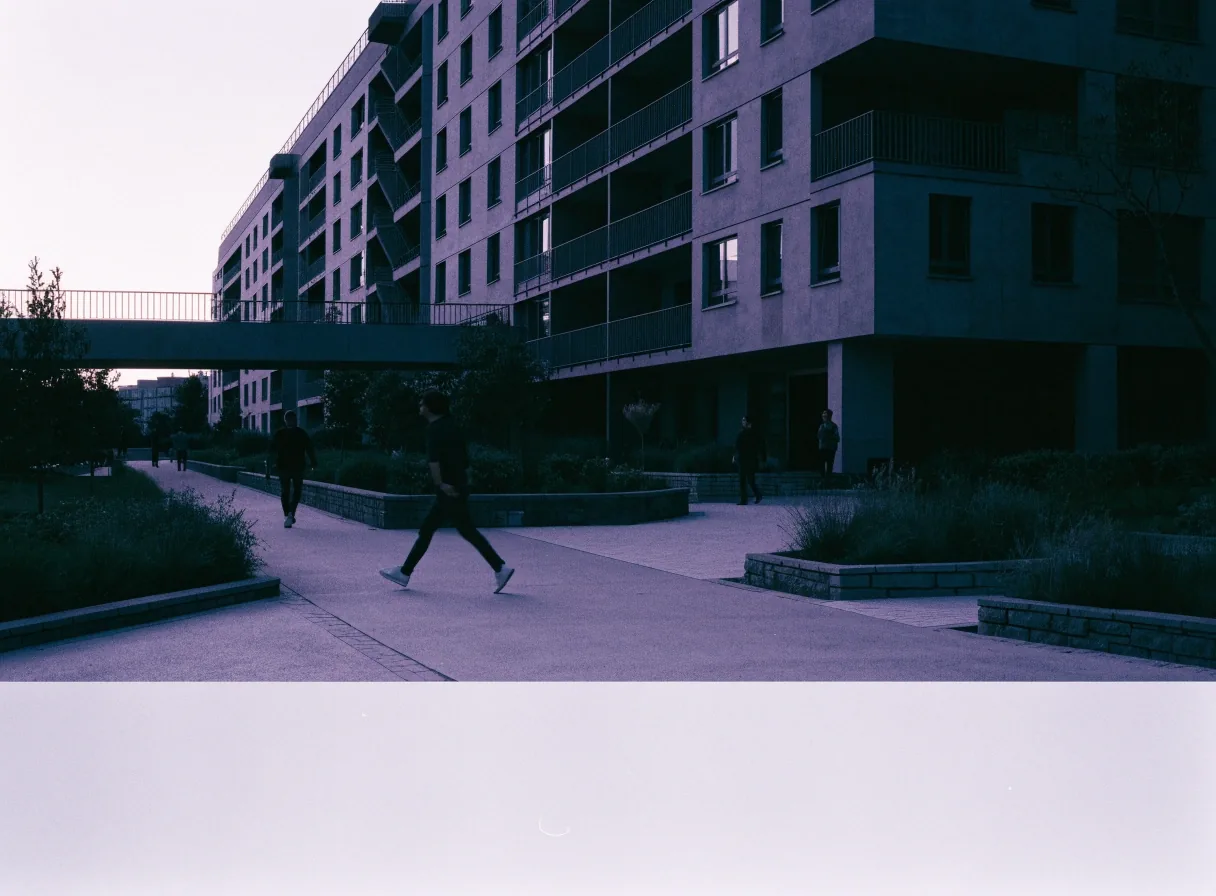
New multifamily development exterior

Supported by housing need in many corridors, multifamily is judged on who is moving in, what they pay, and how long they stay.

Retail — leases with scheduled bumps

Retail

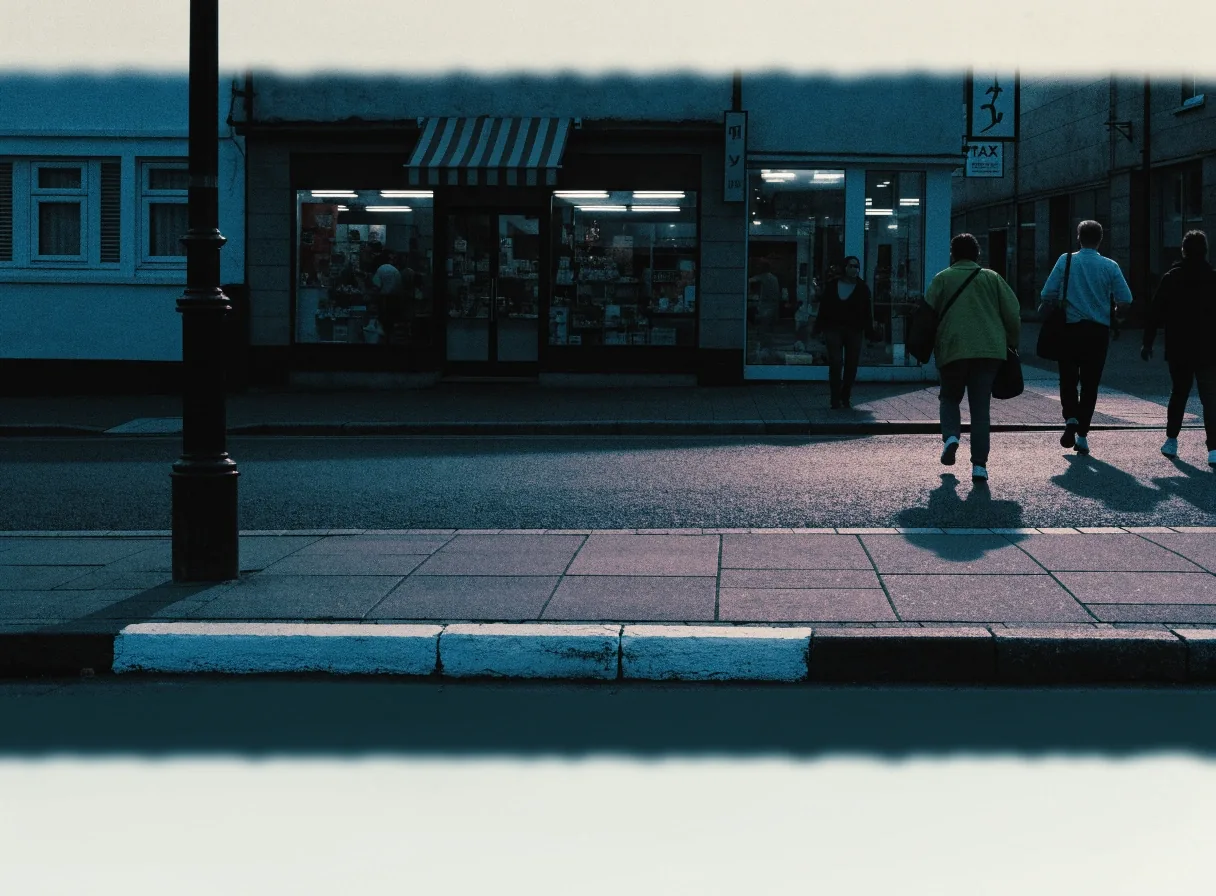
Neighbourhood retail strip with footfall and occupied shopfronts

A retail lease may run for years with scheduled bumps. The question is whether the tenants, the trade area and the lease terms hold together.

Office — flight to quality, older space under pressure

Office

Office leasing floor with desks and meeting space

Tenants upgrade to newer space and leave older buildings behind. We ask what the lease rollover looks like and what the building needs to stay competitive.

Figures, explained

Three figures we never use alone

Cap rate = NOI ÷ price

Cap rate without the shortcuts

A cap rate divides net operating income by price, and that simple division carries a lot of weight. It lets you compare a stabilized retail center with a multifamily asset on the same page, using income rather than square footage. It does not tell you about lease rollover, capital spending, or debt costs, so we never use it alone. A low cap rate in a strong location may still work, and a high cap rate may signal trouble you have not seen yet. We label what the figure can and cannot prove.

Cash flow after debt service

Cash flow after debt, not before it

Investors often quote income before debt service, which flatters the return and hides the risk. We look at cash flow after debt because that is the cash left in the account after the lender is paid. Debt availability in 2026 is better than it was at the tightest point of the rate rise, yet terms still vary by property type and sponsor strength. A deal that needs generous assumptions to cover its loan deserves a harder look. We would rather discard a property early than explain a shortfall later.

Occupancy & vacancy, read locally

Occupancy and vacancy tell a local story

Occupancy rates describe how much space is filled, and vacancy describes how much is empty, but both need a local reading. Leasing demand increasingly follows places where high-value jobs and wage gains are concentrated, so we check employment before we check asking rents. Flight to quality also matters, as tenants upgrade to newer space and leave older buildings behind. We ask who is moving in, who is moving out, and why.

Evaluation as a physical act

How we screen a property before underwriting

Screening is the first filter, and it is meant to be fast and honest. We check location, property type, in-place income, occupancy, and the age and condition of the building against a short list of criteria. Properties that fail on location or income quality do not move forward, however attractive the pitch. This step saves time for everyone, including the seller, because a clear no early is better than a slow maybe. Only properties that pass screening receive a full underwriting.

See our process
Deal-room desk with a massing model and paper files

The desk is where the figures are challenged. A model that cannot be explained in plain terms is not a model we trust.

Debt availability shapes what is possible

Debt is not a footnote in commercial real estate. It determines how much equity a purchase needs, how much cash remains each year, and how much room exists when a tenant leaves. Lenders in 2026 are open to quality assets, but they price risk by sector, location, and track record. Industrial and multifamily properties often face different terms than office, and older office space faces the hardest questions. We check debt terms early, in basis points and in total cost, so financing does not surprise us at the end.

Risk questions we ask out loud

Every property carries risk, and the useful question is which risks you can name and which you cannot. Lease expiration, tenant concentration, rising insurance, deferred maintenance, and local supply are risks we can measure. Regulatory change and sudden shifts in employment are harder to measure, so we keep a margin for them. We also ask what happens if the exit market is slower than expected. A plan that only works in a strong market is a fragile plan.

Start an inquiry

How to start an inquiry with us

If you own a property, represent one, or want to discuss how we evaluate commercial real estate, contact us through the form on this site or write to [email protected]. Please include the property type, location, size, current occupancy, and any known lease or financing details. That information lets our Irvine team respond with substance instead of generalities.

We do not publish listings, and we do not claim inventory we have not documented. An inquiry starts a conversation, and the numbers decide whether it continues.

Address
15320 Barranca Pkwy, Ste 100, Irvine, CA 92618
Hours
Monday to Friday, 9:00 AM to 6:00 PM

What this site will and will not do

This site explains how we think about real estate investment in California and in the wider U.S. market. It does not offer personal investment advice, and it does not promise appreciation, income, or resale outcomes. Market articles are dated and sourced so you can judge their relevance, and older material is updated or retired as conditions change.

NOI first Cap rate with limits labelled Cash flow after debt Occupancy checked locally

Questions, answered plainly

The short answers below are the same ones we give in the first conversation. For the fuller set, see the FAQ page.

What does ADVANCED MARQUIS, LLC do?

ADVANCED MARQUIS, LLC is a real estate investment company in Irvine, California. We provide educational market insights and evaluate commercial real estate using underwriting, cash flow, and risk considerations.

Does this site list properties for sale?

No. This site explains our approach and market perspective. It does not publish a listing inventory, and we do not present properties we have not documented.

How should I contact the company?

Use the inquiry form on the contact page or write to [email protected]. Our office is at 15320 Barranca Parkway, Suite 100, Irvine, CA 92618.