ADVANCED MARQUIS, LLC Advanced Marquis LLC · Irvine, California
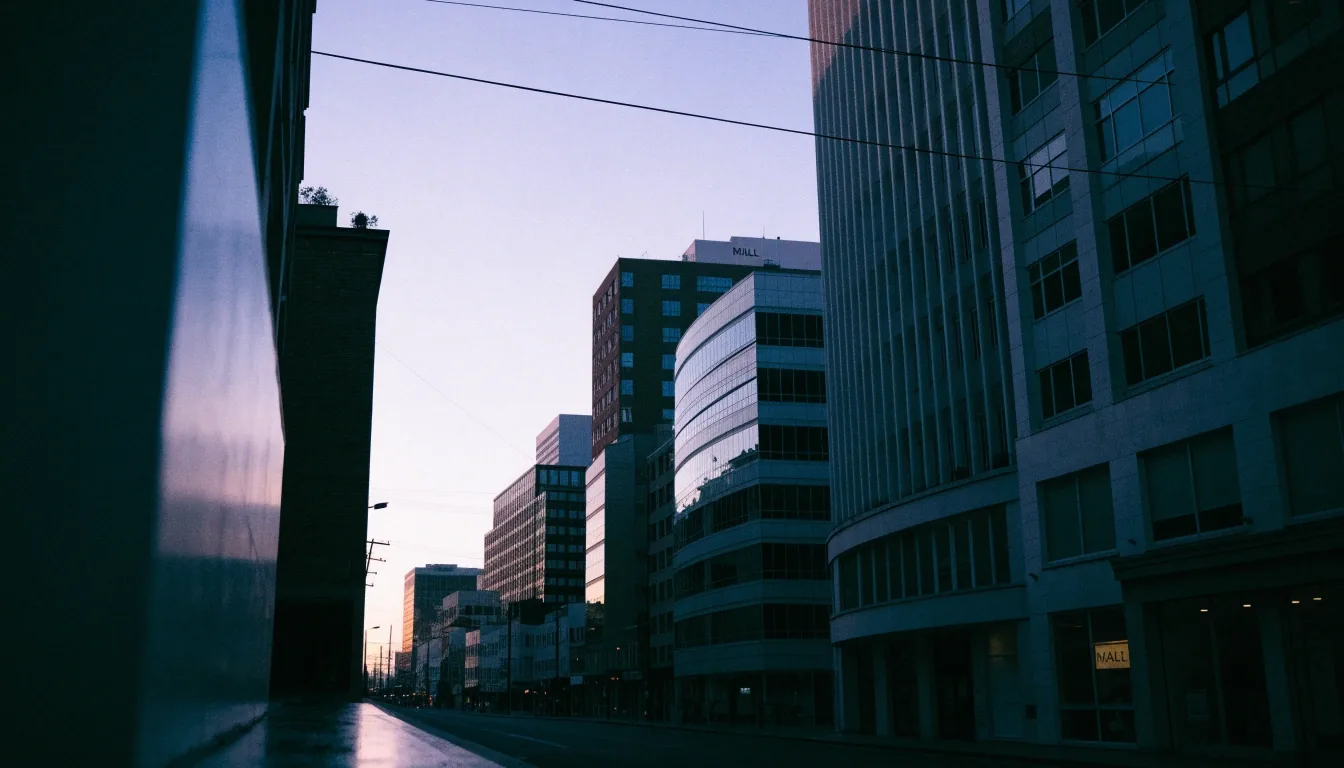
Mid-market commercial buildings in Irvine under morning light

Sectors we follow · Irvine, California

Yield first. The building comes second.

We compare four property types by how they earn, how they fill, and how lenders price them — before we talk about any single building.

What this page covers

Multifamily, retail, office, and industrial compared by fundamentals

Four property types dominate commercial real estate, and they earn money in different ways. Multifamily collects rent from many small tenants, retail collects from stores and restaurants, office collects from companies, and industrial collects from logistics users. Comparing them requires more than a single headline. This page compares fundamentals, demand drivers, and watchouts so you can see why one sector can be strong while another is still adjusting.

NOI · net operating income CASH FLOW · after debt service OCCUPANCY · by submarket CAP RATE · paired with lease story

The comparison in one line

One sector can be strong while another is still adjusting.

That is normal. Housing need, trade-area spending, office attendance, and goods movement do not move on the same calendar. A useful comparison keeps each sector inside its own submarket, its own leases, and its own supply pipeline — and only then asks what the yield is paying for.

Four ways income is earned

The sectors, side by side

Each plate below answers the same four questions: who pays, what fills the space, how quickly income resets, and what can leave it empty.

Multifamily · many small tenants

Multifamily and the housing need behind it

Multifamily properties house the majority of renters, and demand follows population, job growth, and the gap between housing supply and household formation. Where construction has slowed, existing apartments face less competition and vacancy can tighten. Where a large pipeline is delivering, even a strong market can absorb new units slowly. Lease terms are usually short, so income resets quickly with the market. That flexibility helps in rising rents and hurts in a downturn. We check local supply deliveries before we trust any vacancy figure.

Watch: supply deliveries · lease resets · household formation

Retail · stores and restaurants

Retail and the trade area test

Retail income depends on a trade area — the income and spending of people who live and work nearby. A center anchored by grocery and services behaves differently from a center dependent on discretionary shopping. Tenants sign longer leases than apartment tenants, which stabilizes income but slows adjustment when conditions change. We look closely at tenant mix, lease expirations, and the health of the surrounding corridor in Irvine and across Orange County.

Watch: tenant mix · expirations · corridor health

Office · companies, location by location

Office and a recovery in only some markets

Office is improving in a few markets while stabilizing or struggling in others, and that split is the story. Employers deciding how much space to use weigh collaboration, attendance, and cost in each location. High-quality buildings in strong job centers attract tenants who are upgrading, a pattern called flight to quality. Older buildings without modern systems or amenities face higher vacancy and costly upgrades. We treat office as a location-by-location decision, never as a national call.

Watch: attendance · building quality · upgrade cost

Industrial · logistics users

Industrial and logistics after the supply boom

Industrial demand is supported by reshoring, e-commerce distribution, and the need to move goods efficiently. Prologis, one of the largest industrial REITs globally, is a common barometer for this sector. After a period of heavy construction, some submarkets now have more space than local demand requires. That is why we separate logistics corridors that serve large population centers from speculative space in thin markets. Ceiling height, truck access, and proximity to highways matter in ways that office features do not.

Field note · A corridor serving a large population center and a speculative building in a thin market can both carry the label industrial. The demand behind them is not the same.

Watch: corridor demand · ceiling height · truck access
Reading the same words differently

What the shared figures actually mean

Comparing occupancy and vacancy across sectors

Occupancy and vacancy mean the same words in each sector and different things in practice. A 5% vacancy rate in multifamily may signal a soft market, while the same rate in industrial may signal balance. Lease length changes the meaning too, because space that is vacant today may be committed under a lease that starts next year. We compare vacancy only within a sector and a submarket, never across sectors as if the figures were interchangeable. The local supply pipeline is the missing half of every vacancy figure.

Cap rates and how markets price each type

Investors price each sector according to perceived risk, growth, and the cost of debt. Industrial and multifamily assets often trade at lower cap rates than office because buyers expect steadier leasing, though that pattern shifts with rates. Retail pricing depends heavily on tenant quality and lease term. Office pricing reflects the widest range, since top buildings and older buildings face different futures. A cap rate comparison that ignores those differences will mislead. We always pair the yield figure with the lease and location story behind it.

Debt availability by property type

Lenders lend against expected income stability, and they favor sectors with visible tenant demand. In 2026, debt is available for quality industrial, multifamily, and well-leased retail, while older office faces stricter terms and more equity. That difference affects purchase price, because a buyer who must use more equity needs a stronger return to proceed. It also affects refinancing, since a loan that cannot be replaced on time can force a sale. We check debt terms for each sector separately, in basis points and in total cost.

Flight to quality and what it leaves behind

Flight to quality describes tenants choosing newer, better-located space over older buildings. It strengthens top-tier properties while raising vacancy in the stock that tenants leave. This pattern appears in office most visibly, but it also touches retail centers and older industrial space. For an investor, the question is whether a property is the destination or the departure point. Buildings that need heavy capital to compete must be priced to reflect that need. Assuming tenants will stay in outdated space is rarely a safe plan.

Next step

Compare a sector before you compare a building.

If you are weighing multifamily, retail, office, or industrial exposure, start with the fundamentals above — then bring the specific submarket, lease, and debt terms to the Irvine team. We will look at the same figures, in the same order.

Advanced Marquis, LLC

15320 Barranca Parkway, Suite 100
Irvine, CA 92618

Monday to Friday, 9:00 AM to 6:00 PM

[email protected]
+1 (949) 513-6138

NOICASH FLOWOCCUPANCYYIELD FIRST · BUILDING SECOND